Historic Tax Credit Ownership Flip: Structure and Safe Harbor Guidance
By Aaron Mayer, Director of Sherbert Consulting and Moxie Investments amayer@sherbertconsulting.com
The federal Historic Tax Credit (“HTC”) provides a meaningful incentive for the rehabilitation of certified historic structures, but the mechanics of how investors access it are often misunderstood. A key structural concept in HTC transactions is the “ownership flip” – a mechanism that governs how equity interest in a project shifts between investor and developer. This article explains how ownership flips work, why they exist, and the safe harbor guidance that governs their treatment.
The Federal Historic Tax Credit (Section 47): A Brief Overview
Section 47 of the Internal Revenue Code provides a tax credit equal to 20% of qualified rehabilitation expenditures (“QREs”) incurred in connection with the historic rehabilitation of a certified historic structure. The credit is claimed by the taxpayer that owns the building at placement-in-service, and ownership must be maintained throughout the subsequent five-year recapture period.
The practical challenge: many real estate developers don’t have sufficient federal tax liability to make effective use of the credit. This creates the need for a tax credit investor — typically a bank or corporate entity with significant federal tax liability — who contributes equity capital in exchange for an allocated share of the partnership’s income, gain, loss, deduction, and credits.
Why the Ownership Flip Exists
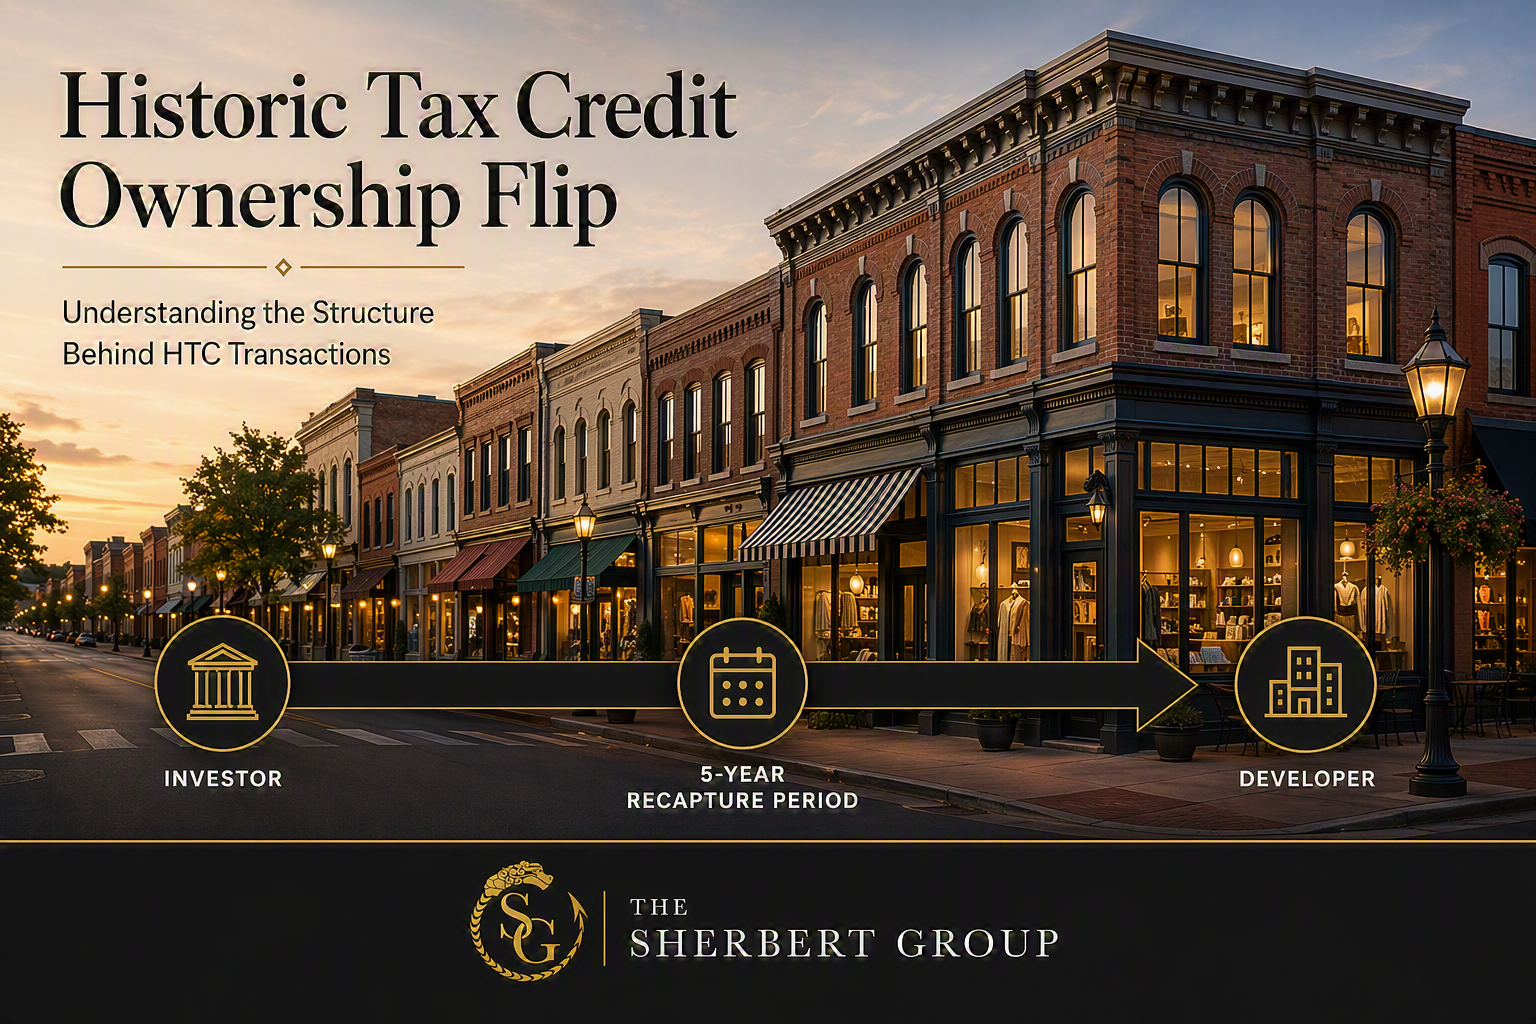
In a typical HTC transaction, the project is owned by a partnership or LLC. The investor enters the ownership structure holding a majority economic interest (commonly 99%) throughout the period when credits are claimed and recapture risk remains active. This ensures the investor holds a meaningful ownership stake commensurate with the tax benefits allocated to it.
After the five-year recapture period concludes, recapture risk has expired and the investor’s largest benefit has been secured. At that point, the structure may be designed to “flip”: the developer (or a developer affiliate) acquires majority ownership, and the investor’s interest is reduced substantially while the investor continues to participate as a partner. Many transactions also pair the flip with a put right, through which the investor may require the sponsor to purchase its remaining interest.
This structure serves both parties’ objectives, with the investor receiving its anticipated tax benefits during the credit and recapture period, and the developer acquiring majority ownership of the asset following the flip.
Revenue Procedure 2014-12: The Safe Harbor
Prior to 2014, the structuring of HTC transactions with ownership flips relied on general partnership tax principles and analogous guidance from other tax credit programs. No IRS guidance specifically addressed whether the HTC flip mechanism would be respected for federal tax purposes.
Revenue Procedure 2014-12 (the “Rev. Proc.”) filled that gap. Effective for transactions with a placement-in-service date on or after December 30, 2013, it established a safe harbor under which the IRS would not challenge the allocation of HTCs to a partnership investor. Compliance is elective – a transaction outside the safe harbor may still be respected on a facts-and-circumstances basis – but satisfying the Rev. Proc. provides a meaningful degree of transactional certainty.
Safe Harbor Requirements
To qualify, an HTC transaction must satisfy requirements across a number of areas, including:
- Principal’s minimum interest
- Investor’s minimum interest
- Allowable fees and lease terms
- Investor’s minimum contributions
- Permissible guarantees
- Purchase and sale rights
A comprehensive review of these requirements is beyond the scope of this article; each should be examined carefully during transaction structuring.
The Flip Under the Safe Harbor
Revenue Procedure 2014-12 expressly accommodates the ownership flip. After the compliance period, the investor’s interest may be reduced to as low as 5% of its maximum allocation for each material item of income, gain, loss, deduction, and credit — provided all other safe harbor requirements remain satisfied throughout the life of the partnership. The Rev. Proc. includes an illustrative example in which the investor’s interest begins at 99% and is reduced to 5% at the end of the recapture period.
This provision formally confirms what practitioners had long structured in practice: a post-compliance reduction in the investor’s interest, on its own, does not disqualify a transaction from safe harbor protection.
Timing Is Critical: The Recapture Risk
One constraint warrants particular attention. The ownership flip must not take effect before the end of the five-year recapture period under §50(a). An early reduction in the investor’s interest – even one otherwise consistent with the Rev. Proc. – could trigger credit recapture. Careful attention to flip trigger and timing provisions in the partnership agreement is essential.
Frequently Asked Questions
What is the ownership flip in an HTC transaction? The ownership flip is the contractual reduction of the investor’s interest in the project entity following the five-year HTC recapture period, at which point the developer (or a developer affiliate) acquires majority ownership while the investor continues to participate as a partner.
When can the ownership flip occur? The flip should not take effect before the end of the five-year recapture period under §50(a). An early reduction in the investor’s interest may trigger credit recapture.
Is compliance with Revenue Procedure 2014-12 required? No, compliance is elective. However, satisfying the safe harbor provides significant certainty that the IRS will not challenge the credit allocation. Transactions outside the safe harbor may still be respected based on facts and circumstances. It is worth noting that the safe harbor’s requirements extend well beyond the flip mechanics and should be reviewed early in the structuring process.
The information in this article is based on law in effect as of the date of publication and is subject to change. It is intended for general informational purposes and does not constitute legal or tax advice. Consult The Sherbert Group or another qualified tax professional regarding the specifics of any HTC transaction.
RELATED READING
Info on Sherbert Consulting: https://www.sherbertgroup.com/sherbert-consulting/
Article on the HTC substantial rehab test: https://www.sherbertgroup.com/substantial-rehabilitation-test-qualify-for-20-historic-tax-credit/